Scholarship houses
Real estate that produces deductions and income, with the work done for you, even if you are a W-2 or 1099 employee.
Why your advisor never mentioned real estate
I spent 20 years as a traditional financial advisor. I never recommended real estate, for two honest reasons: I knew nothing about it, and I was not paid to. The industry does not teach it, because planners and the brokerages behind them earn nothing when you buy a building.
I saw it work in my own family. My dad was an accountant for a property management company. His income peaked around $60,000 and he retired at 57 with $50,000 in his 401(k). What let him retire was a loan he took years earlier to buy into some of the real estate alongside his boss.
When he died at 72, the cash flow did not stop. It passed to my mother, it will pass to the three of us, and then to our kids.
How a scholarship house works
Real estate does five things at once. These are the three that have to happen in order.
-
We find it and run the numbers
Our team sources the property in a market that supports nightly rental, analyses the data for the revenue projection, and handles the purchase and ownership transition.
-
A study front-loads the deduction
A cost segregation study breaks the property into its 5, 7 and 15 year components. With bonus depreciation at 100 percent, those come in year one rather than across 27.5 or 39.
-
It runs, and it pays
Renovation, design, guest management and pricing are handled for you. What you own is an asset producing deductions now and income for as long as you hold it.
Why the tax treatment is different
Equipment genuinely wears out. Real estate usually does not lose value, even though the tax code treats it as though it does. So you are buying something that tends to rise in value and produces income, while the government gives you a deduction for owning it, because it wants housing to exist.
It does not work quite like equipment, though. Land cannot be depreciated at all, and a building is not one item: the foundation, roof, flooring, fixtures, appliances and landscaping each have their own schedule. People assume a cost segregation study is a grey area that invites scrutiny. It is a standard engineering study, and what it changes is timing, not the total.
A study on a property I bought
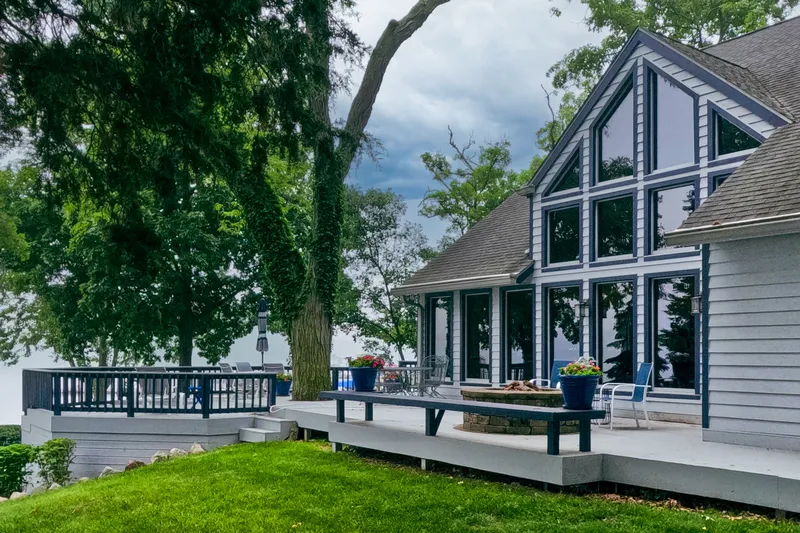
A cabin in Idaho, bought for $1,495,000. Here is what the cost segregation study released in the first year.
$456,853deductible in year one
Without the study the whole building would sit on the 39 year schedule and the first year would release a small fraction of that. A cost segregation study does not change what you are entitled to deduct in total. It changes when you can take it.
This is one property in one tax year, shown to make the mechanics concrete. It is not a projection of what any other property would produce.
| Purchase price | $1,495,000 |
|---|---|
| Land allocation | $299,000 |
| Unadjusted basis for the study | $1,196,000 |
| Depreciation available in year one | $456,853 |
Would a scholarship house work against your tax position?
Book a free strategy callDoes this work for a W-2 employee?
Yes, and this is where the detail matters. Most rental income is passive, and passive losses generally offset passive income only, so a long-term landlord cannot use depreciation against wages.
Short-term rentals are treated differently. Where the average guest stay is seven days or less, the tax code stops seeing a rental property and starts seeing a mini hotel, because you are checking guests in and out continuously. That reclassification is the whole mechanism: a hotel is a business you actively run, and losses from a business you actively run can reach the income on your W-2. People call this the short-term rental loophole. It is not a loophole, it is the category the activity belongs to.
Who does what
What our team handles
- Finding the property and running the market data for the revenue projection.
- The purchase, the ownership transition and any renovation.
- Interior design, guest management and ongoing pricing optimization.
What cannot be handed over
- Material participation. If the depreciation is to reach your active income, you have to meet one of the tests yourself and evidence it.
- The usual test is 100 hours where no other individual spends more time than you, or 50 hours each for a couple filing jointly.
- The reference is Treas. Reg. §1.469-1T(e)(3)(ii)(A). Decide with your CPA how you will meet and document it before you buy, not after.
Where the money comes from
Usually from somewhere it is already sitting. None of this should be decided without your CPA.
Cash in the bank
- No tax and no penalty.
- In most accounts it is not earning much.
- If you have enough sitting there, you are done.
529 accounts
- Beyond the qualified education expenses you pay tax and a 10 percent penalty on the gains, not on the whole balance.
- That penalty is what makes most people pay cash and drain the account instead.
- Money put into an asset can carry a deduction with it, which is what offsets the cost of getting it out.
Retirement accounts
- In a year with qualified education expenses the early distribution penalty does not apply before 59 and a half, though income tax applies to all of it.
- If a study lowers your income by a similar amount, the year is close to a wash.
- The IRA money had never been taxed. You have used the deduction to settle the tax on it.
What the properties look like
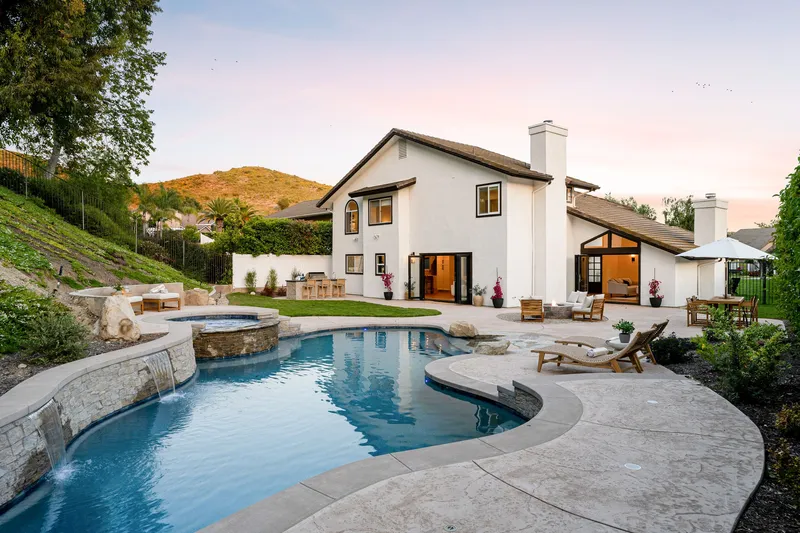
These are ordinary houses in markets that support nightly rental, not a different asset class. The difference is who does the work. Our design team builds the guest experience that earns the reviews, the management company runs the stays, and the revenue team adjusts pricing to keep the nightly rate and the occupancy where they need to be.
That is the whole reason the team exists. I was not going to become a property operator in my spare time, and neither are you.
The risks, plainly
Every investment carries risk. Property values can fall, a property can sit empty, and in a bad month the rent may not cover the mortgage and the expenses. Financing increases both the return and the exposure, and short-term rental income depends on local regulation, which can change.
Selling triggers recapture on the depreciation you claimed, unless you roll the proceeds into more real estate through a 1031 exchange, which defers it and can be repeated. Beneficiaries also inherit at current value, so if they sell, tax applies to the gain from when they inherited rather than from what you paid.
From a family who did this
For a small investment, I have experienced a 1,000% return and discovered the most brilliant strategy to pay for college while building real, generational wealth.
These are the experiences of individual Legetty clients, in their own words. Individual results depend entirely on your own income, tax position and circumstances, and nothing here is a guarantee, a projection or a typical result. Figures mentioned are what those clients say happened to them, not what this site offers or predicts.
We wanted to make investing in real estate as easy as investing in the stock market. We do all the hard work, and you do all the easy stuff.
Lance Morgan, founder
All four strategies
Each one helps on its own. Combined, the savings from one pay for the next.
- Tax scholarshipsTurn part of the annual tax bill into assets you own.
- Student and financial positioningLower what college costs by positioning the student and the assets.
- Scholarship housesProperty that produces deductions and cash flow, run for you.
- Leave a legacyPay for college without interrupting your own compounding.
Book a free strategy call
Tell us about your family, your income, and when the first tuition bill lands. We will walk through which of the four strategies apply to you, and what putting them in place would involve.